Wednesday, 13 June 2018

New Book: A Brief Affectionate History of the Financial Markets Group

As many of my friends and peers already know, I took an academic sabbatical in the fall of 2015 to gain a Masters degree in Medieval History from King's College London.  The courses were hugely challenging - especially Intermediate Latin and the Medieval Latin Translation Seminar - but also hugely rewarding.  Dr Daniel Hadas edited my transcription and translation of the Carmen Widonis 25 lines per week during the academic year, allowing me to produce the most literal and accurate translation of the earliest and most detailed account of the Norman Conquest.  I am particularly proud of re-interpreting the 1066 siege of London as resulting directly in the truce that yielded the Charter of London's Liberties, the first civil rights act to grant state prerogatives to a citizenry and the basis for a mercantile common law.  I also change the landscape of the Norman Conquest, shifting the fleet landing, camp and battlefield into the Brede Valley, then a great estuarine sandy loch -  Senlac.  The republished work is now available on Amazon as Carmen de Triumpho Normannico - The Song of the Norman Conquest, which includes four appendices giving detailed original research into the backstory, motivations, geography and political context of 1066.


Before I could get back to work in financial market infrastructures I was asked to undertake another history, and I couldn't refuse.  Professor Charles Goodhart has been a friend and mentor since I first came to London in 1990.  His contributions to the central banking world as chief economist of the Bank of England, founder member of the Monetary Policy Committee, and member of the Financial Stability Board are awesome.  At 80 he is still going strong.  Together we have produced A Brief Affectionate History of the Financial Markets Group, celebrating 30 years of the Financial Markets Group, the London School of Economics centre of excellence for the study of financial economics.  Mervyn King, now Baron of Lothbury, was a co-founder of the FMG in 1987, and wrote the Foreword for the book.  A very young Mervyn is also on the cover.
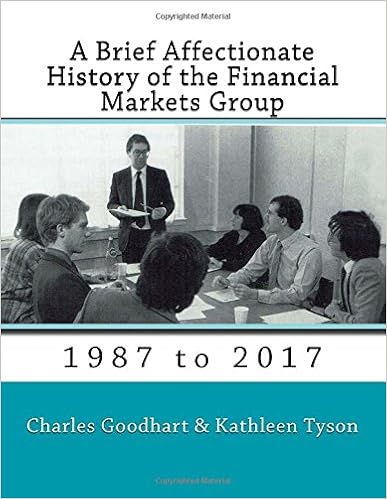


The book is unlikely to be of interest to anyone who wasn't involved in FMG over the years, but since there are over 1400 Economics professionals, central bankers, and academics who were involved in FMG, I hope some of them will enjoy it.  In addition to reviewing the set up and participation in FMG, the lists of Discussion Papers and Special Papers offer a useful retrospective of the development of Financial Economics as a discipline.  FMG has made a huge contribution to the rigorous methodologies we have today.


In any event, it was lovely working with Charles, and proving a history degree can have some value.  We've been wanting to write something together for years, and this was a great project for partnering our different skills usefully.


Now I'm back and ready to take on the challenges of modernising financial markets infrastructures to meet the PFMIs and new regulations such as GDPR, PSD2 and Basel III, as well as the evolving opportunities and threats of emerging technologies.  Last year's paper on DVP on DLT: Linking Cash and Securities for Delivery vs Payment Settlement in Distributed Ledger Arrangements with Rise Technologies has had over 1000 readers, which is very good for a technical white paper, and I've published several topical articles on financial market developments in Financial World, so hopefully I can show I've stayed current with the infrastructure landscape of the financial markets while re-writing the landscape of 1066 and bringing the financial economics landscape into focus.

Monday, 6 March 2017

DVP Securities Settlement on DLT White Paper

Granularity has been pleased to collaborate with RISE Financial Technologies to compose a white paper on DVP on DLT: Linking Cash and Securities for Delivery vs Payment Settlement in Distributed Ledger Arrangements.  RISE won the SIBOS 2016 SWIFT Innotribe Challenge to bring the blockchain to securities post-trade processing and is now proceeding with a proof of concept of its DVP on DLT solution for SWIFT and potential customers.

The link for the DVP on DLT paper is:  https://docsend.com/view/c9uand3.

The aim of the white paper is to show the current feasibility of integrating DVP on DLT with legacy centralised settlement operations for better near real-time settlements, operations and security, and to signpost some of the challenges of DLT integration and migration.  We expect a phased progression to DLT settlements respecting existing settlement system operations and the CPMI-IOSCO Principles for Financial Market Infrastructures.

Please feel free to forward and share this white paper with colleagues or others you believe will find it of interest.

We would welcome your feedback or questions as we recognise that this is an area where technology is moving at a rapid pace and legal and regulatory models are still evolving to meet the challenges.

If you have questions, comments or would like more information on RISE solution feasibility, please feel free to contact me.
   

Saturday, 31 January 2015

Polaris/Intellect win Central Banker Award 2015 for Technology Provider of the Year!

I've known for a few weeks, but I had to wait until it was on the Central Banker website to blog it.  My client Polaris Financial Technology and its software solutions subsidiary Intellect Design have won the 2015 Central Banker Award for Technology Provider of the Year.  I'm delighted for everyone who has been working so hard to make the Quantum Central Bank Solution and the Quantum Collateral Management Solution the best practice standards for central bank technology modernisations.

This award is recognition that we've got the right solutions at the right time to bring central banks into the 21st century - with real time operations, risk management, transparency and interaction with market infrastructure.  For more than two years now I've been working with the team there to enrich the QCBS solution as the Strategic Advisor for Central Banks and Market Infrastructure, having approached them after seeing a presentation on the scope and effectiveness of the transformation at Reserve Bank of India.

RBI was an enormously complicated central bank, with over 30,000 staff in 28 branches, each of which had its own inconsistent data centres, applications and IT processes before the modernisation.  Besides the normal core banking challenges and financial infrastructure services of central banks, RBI also manages all government accounts in India for all departments, agencies, and everything else, meaning it had a huge clientele and a huge complexity challenge interfaced to real economy.  Nothing happened in real time.  There were many manual processes and end-of-day handovers between systems.  It took three weeks to compile the general ledger at year end.

Now everything is on a single integrated platform that provides real time visibility of operations, exceptions management, risk management and produces an up to the minute enterprise general ledger that can be prepared for management and government scrutiny on demand.  The modernisation of the systems has enabled the central bank to meet the challenges of a rapidly growing and evolving Indian economy in times of global financial instability.  For example, payments volumes processed by the central bank have risen from 2,589 million transactions annually before the modernisation to 1,499,269 million translactions annually in 2014, demonstrating the effectiveness of new collateralisation and credit facilities to support better financial infrastructure.  The Quantum Central Bank Solution platform is benchmarked to handle more than 105 million transactions per day, providing plenty of scope for growing the real time services more bank and government clients are demanding.

One of my favourite things about the solution is that there is an integrated real time data store enriched with events as they are processed so that all applications see up to date data for better operations and risk management.  That means there is no longer any complicated middleware servicing multiple inconsistent applications and generating reconciliation errors and end of day headaches for staff.  It also means integration with external parties such as payment systems, clearing houses, peer central banks, correspondent central banks, custodians and central securities depositories is better managed and better serviced.  That makes a big difference in this globalised world of ours.

The solution also uses native XML and is future-proofed to ISO 20022, making the Reserve Bank of India the most modern central bank in one giant step forward for technology migration.

Better yet, the system has low total cost of ownership.  The internal IT department owns the workflow configuration and application parameters, so that they can maintain and adapt solutions over time to meet changing requirements without going back to the vendor for change control.  Change control for inconsistent, customised applications is an expensive head ache most central banks and financial infrastructure operators know too well.  Having a future proof system that your own IT team controls and services is a major advantage in meeting evolving challenges without stress. 

And did I mention the entire modernisation at Reserve Bank of India was accomplished in less than 20 months from contract signing to delivery of the last module, the now very popular Public Debt Management System?  The first module, the Enterprise General Ledger was delivered in just 6 weeks, providing real time visibility of all government revenues and expenditure as well as central bank core banking operations.  Besides have great solutions, Polaris/Intellect have a great integration support team and disciplined and effective methodologies for project management and technology migration.

Last year we won the tender to modernise Riksbank and enrich its risk management with the Quantum Collateral Management System.  The solution will provide a flexible, configurable virtual collateral pool that links to all regional CSDs, Euroclear, Clearstream and payments platforms in real time.  It is a step change in collateral management that will benefit everyone reliant on the central bank for liquidity and efficient collateral services.  They are our first central bank in Europe, but I am sure many others will want to join them when the advantages of the new platform are fully understood.

Well done Polaris!  I had planned to be on holiday the week of the award ceremony, but have already booked my flights to come back to London on 12th March for the awards ceremony and dinner.  I want to be there with my team to enjoy their well deserved moment in the spot light.

Monday, 21 April 2014

Nothing Rotten in Denmark

The Economist has taken a whack at the indebtedness of Danish homeowners, suggesting fragility in Denmark to interest rate rises.  In response I've sent the following letter to the editor:

Re: Danish Mortgages - Something Rotten

Sir,

Danish mortgage bonds have outperformed US Treasuries and all other government debt since the start of the financial crisis in 2008.  Rather than being backed by the theoretical capacity of governments to raise taxes on struggling economies, Danish mortgage bonds are backed by real properties with sensible valuations, 20 per cent down payments by borrowers, and a system of transparent market finance that has not experienced a bond default in over 200 years.

The level of Danish private mortgage debt may be high, but Danish borrowers are being urged to refinance at low fixed rates.  Danish banks are doing the urging because they can finance mortgage loans in the liquid bond market.  Even if a property bubble bursts, Danish borrowers who cannot meet loan payment obligations will typically sell at a profit rather than default.  When a much larger bubble burst in the 1990s borrowers with 3 months arrears peaked at less than 2 per cent.


Kathleen Tyson Quah
Granularity Ltd
London

Saturday, 30 June 2012

The ESMA OTC Derivatives End User Exclusion

ESMA has released a Consultation Paper on the draft technical standards for trade repositories, OTC clearing and CCPs.

Discussion of non-financial counterparty exclusions begins on page 14.

OTC contracts that protect non-financial counterparties against risks "directly related to their commercial activities and treasury financing activities" are entirely excluded from a CCP clearing obligation.  OTC derivatives that do not protect against "directly related" risks but do not exceed clearing thresholds are also exempt from the clearing obligation.

To be "directly related" and therefore excluded from theshold computation, OTC derivatives contracts of a non-financial counterparty must be "objectively measurable as reducing risks directly related to its commercial activity or treasury financing activity or that of its group." There are two alternative tests for exclusion.  The first test is whether the OTC derivatives contract of the non-financial counterparty "individually, or in combination with other derivatives contracts", reduces "the potential change in the value of assets, services, inputs, products, commodities, liabilities that it owns, produces, manufactures, processes, provides, purchases, merchandises, leases, sells or incurs in the ordinary course of its business, or the potential change in the value of assets, services, inputs, products, commodities or liabilities referred to above, resulting from fluctuation of interest rates, inflation or foreign exchang rates."  The second test is whether the OTC derivatives contract qualifies for accounting treatment of a hedging contract under IFRS principles endorsed by the European Commission.  The rules are clear that whether the contracts consitute hedging under local GAAP rules is the standard, although ESMA expects most local GAAP treatment to meet the proposed definition.

If OTC derivatives contracts are not excluded, they count toward thresholds for clearing.  Clearing thresholds are set by notional amount and by asset class, with 5 asset classes defined: credit, equity, interest rates, foreign exchange, and commodity & others.  Breaching the threhold for any one asset class subjects the non-financial counterparty to a clearing obligation for all derivatives for all asset classes thereafter.  The notional amount thresholds will be phased-in, and periodically reviewed.

Non-financial counterparties will have to confirm OTC derivatives contracts by the end of the second business day following the trade day.

Portfolio reconciliation must be daily if counterparties have more than 500 contracts between them, weekly if between 300 and 500 contracts, and monthly for less than 300 contracts.

Portfolio compression is mandated for all counterparties with more than 500 non-centrally cleared contracts to be done at least twice a year.

Capital treatment will be addressed in a separate set of regulations on Basel III and CVAs.  There is still a significant likelihood that exclusion from clearing will result in a requirement of higher bilateral margin and contract re-pricing to include the CVA.

Much more in there, but this hits the high points.

Tuesday, 19 June 2012

Hurtling Towards Harmonisation

I spent most of yesterday reading the Financial Stability Board's OTC Derivatives Markets Reforms Third Progress Report on Implementation.  Thrilling stuff if you were desperately awaiting your next installment of regulatory waffle on harmonisation of global regulation and infrastructure for derivatives.

What struck me most powerfully about this report was the weakness of the policy agenda ("improve transparency in the derivatives markets, mitigate systemic risk, and protect against market abuse" and motherhood and applie pie) and the absoluteness of the policy prescriptions ("[A]ll jurisdictions and markets need to agressively push ahead to achieve full implementation of market changes by end-2012 to meet the G20 commitments in as many reform areas as possible.").  After all, the global financial crisis was not caused by derivatives.  The financial crisis was caused by abusive securitisation of debt (mostly RMBS) which was impelled by preferential capital treatment under the Basel Capital Accords.

Why all?
Why agressively?
Why full implementation?
Why the deadline of end-2012?

I have been troubled by harmonisation of global regulations as an absolute objective for my entire career.  The Basel Capital Accords always struck me as dangerously simplistic in ignoring the national differences in banking systems.  Perhaps I am alone in thinking that different countries that have made different choices about legal principles and economic interest and market structure could reasonably hold different views about regulatory policy, priorities and practices.

A country like Britain whose banks are mostly giant global behemoths of nearly unmanageable size and complexity has a very different risk profile to countries like Russia or Saudi Arabia where most wealth is generated from resource extraction and the priority is protecting investments and ensuring market access.  Derivatives in London are used mostly for speculative trading and market making by intermediaries.  Derivatives in a resource economy will be mostly used for hedging and trade management.  And yet both are being subjected to absolute rules and absolute infrastructure requirements without regard to native interest or the different risk characteristics presented by empircal market practice and experience.

The report recognises that some countries are asserting native interests in requiring local clearing arrangements (e.g. Japan), but does not explore the policy rationale or recognise legitimate methods for protecting native interests.  Instead any variation from the desired consistency with the orthodox interpretation of requirements is treated as threatening the fabric of international markets (unless the US or central banks are doing it).

There is no recognition in the report of the risks of unintended consequences from implementing these reforms, even though much is being aired in the industry as the deadlines near.  Operational complexity will be massively increased for all market participants by parallel implementation of Legal Entity Identifiers and mandatory trading and clearing reforms.  Liquidity risks are growing daily as the shortage of quality collateral tightens amid downgrades and immobilisations.  Clearing houses are competing on lower margin requirements and taking lower quality assets, increasing the risks of a clearing house failure with massive systemic disruption and/or public bailouts.  Markets are suffering from declining liquidity, high volatility and impaired price discovery as end-users and institutional investors decide to sit on the sidelines to see what sort of markets emerge from the reforms.  Lawyers are struggling with renegotiating and redocumenting literally millions of bilateral agreements with varying terms and constraints into the new standardised construct.  And all of this is happening at a time when banks are undercapitalised, more encumbered than ever, stressed and struggling with both markets and regulators.

Why is "one size fits all" regulatory diktat a bad guiding principle for Communism but an excellent guiding principle for global capitalism?  Wouldn't we be more likely to discover what good public policy looks like if we allowed countries to take different views on market regulation and then compared empirical experience?  Both Denmark and Greece apply all Basle Capital Accord and EU directives, but they have very different financial markets with very different risk profiles.  They certainly have had very different experiences.  Shouldn't we ask what Denmark is doing right that Greece is doing wrong and learn from that, even if it is contrary to prevailing orthodoxy?

More generally, is a global financial system that insists on adherence to orthodoxy a strong system or a weak system?  If the policies are conceived and implemented in error - as the Basel Capital Accords may yet prove to be, no matter how many regulatory careers are built on them - then the adherence to orthodoxy weakens the entire construct and exposes everyone to severe systemic risk.

Given the massive cock ups revealed in the past five years, I'd rather have a period where different countries were free to experiment in legislating and regulating their financial systems than a rush to orthodoxy dictated by the same geniuses who caused the massive cock ups in the first place.  But I guess that's why I'm not a regulator anymore.

Wednesday, 16 May 2012

Derivatives as a Financial Crisis Accelerator

Following links a few days ago led me to a fascinating journal article by Professor Mark Roe of Harvard Law School.  He suggests that the preferential treatment of OTC derivatives and repo collateral transfers in advance of bankruptcy skews incentives to make the financial system much more leveraged and more risky than it would be otherwise.  The top dealers - who have the best overall view of asset portfolios, trading positions and debt structures - can secure cash and assets to themselves through collateralisation, and even fraudulent over-collateralisation, without any risk of challenge in the ensuing bankruptcy.  As a result, they finance much higher levels of systemic leverage and write many more OTC derivatives than they would if they had to actually worry about counterparty failure.  And the failed companies themselves are left with much less of value to satisfy other claimants (employees, pensioners, trade creditors and the government) or to attract investors that might resuccitate the failed firm.  Because repos and OTC derivatives are bilateral and not reported, it is impossible for other creditors of a firm to monitor the exposure of the firm or the pre-insovlency transfers of assets through margin calls to the preferred secured creditors.  The result is that the market economy becomes progressively less transparent, less resilient and less equitable.

Professor Roe's observation is worth seriously evaluating as it accords very nearly with what we have observed in the five years of financial crisis.  It also helps explain why the crisis stubbornly persists in the face of extraordinary fiscal and monetary policies.  Assets are transferred pre-insolvency to preferred repo and OTC derivatives creditors.  (In the case of Lehman Brothers International, the global market liquidations started in March 2008 as available assets - including customer assets - were liquidated globally to make progressively more demanding margin calls to a handful of preferred creditors.)  Losses are socialised to investors, trade creditors, pensioners and taxpayers, while the dominant global banks continue to record healthy profits.  Investors shy from taking on failed firms as they have in previous downturns, because too little is left worth salvaging.

It may be the situation is still getting worse, rather than better.  In the recent failures of Bear Stearns, AIG, Lehman and MF Global, the failures actually reinforced the dominance of the top incumbents and further concentrate dealing, custody and collateral to these same firms.  They have more market power today than ever, and better vantage should they choose to game the system.

Besides indicting the preferences of the Bankruptcy Code reforms, Professor Roe also suggests that the move toward central counterparty clearing will not improve the situation as hoped.  His objections include:
  • Poor incentives in exchanges and clearing houses to manage risk as they are competitive and owned by the dominant incumbents;
  • Clearing house margining of many OTC derivatives will not fully address credit risk as past experience indicates that many transactions look just fine right up until default is recognised - "jump to default" risk;
  • The risks netted in a clearing house are only netted among direct clearing members, resulting in reallocation of the risks to those outside the circle of direct clearing members while concentrating assets in the hands of fewer and fewer dominant players;
  • Clearing houses "up the ante" on Too Big To Fail by themselves being too big to fail, and concentrating liquidity and assets in the hands of clearing members and settlement banks.

I'd like to believe the work we are undertaking as an industry to implement CCPs will prove risk reducing, making the financial system stronger and more resilient.  But I also believed the same thing when I helped repeal Glass-Steagall and promoted OTC derivatives in my early career as a regulator.  I believed the same thing when I was involved in driving forward the harmonisation of laws on securities ownership, transfer and pledging globally.  I sincerely believed that deregulation and harmonisation would make the world a safer place for capitalism. Legal certainty of transaction enforceability grows markets, and our success in gaining legal recognition of repo, derivatives and their collateral arrangements underpinned the massive global growth in repo and OTC derivatives dealing that defines today's markets.

But capitalism requires risk if capital is to be allocated efficiently.  If the dominant players in the game never lose, because they can always allocate losses to others at the table, then that isn't really capitalism anymore.  The result will be consistent misallocation of capital and inequitable returns to firms that do not contribute to the overall social welfare and economic prosperity.  In a nutshell, this is what the Occupation movement objects to about the current system.

At its core, an economy requires wages be paid for there to be sustainable wealth creation.  As wages grow, so does broader prosperity.  Industries that create jobs and pay more and higher wages to more people contribute more to the greater social good.  Industries that are insensitive to the destruction of jobs, stagnation of wages and deflation of private wealth are bad for society.

Professor Roe suggests that reforms to bankruptcy laws that removed the risk of loss for repo and OTC derivatives counterparties went too far.  The small cohort of repo creditors and OTC derivatives counterparties that dominate global markets became insensitive to the business rationale or commercial prospects of their counterparties so long as they gained possession of enough quality assets as collateral to comfortably cover any credit risk.  Something is clearly wrong in a system where the dominant incumbents never lose while most of us become progressively more exposed to unemployment, pension devaluation, higher taxes and economic insecurity.

Bankruptcy law usually tells the end of a story.  If Professor Roe is right, we might consider whether the bankruptcy preferences created by a generation of visionary capital markets lawyers are somewhere near the beginning of the story of today's global financial crisis.